Service guide Life · Nation
Understand the price of a borrowed dollar
Read the key parts of a credit-card bill and see why interest, payment size, and timing matter.
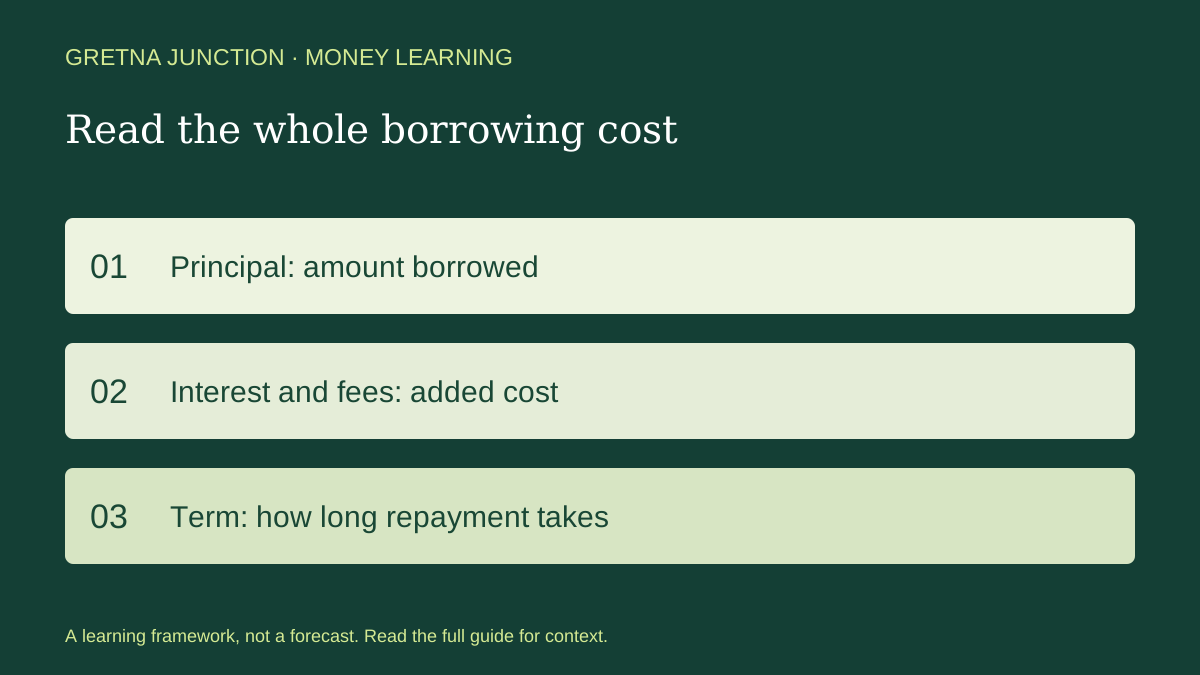
Image provenance · CIE 100/100
Assessment applies to the credited image record and its editorial context. Image delivery, pixels and the pictured event’s current status require separate verification. Receipt: ca8bb698-6d8e-488d-af4c-637ec7534f18
Image & publication standards →In this story
Read the bill before comparing strategies
Start with one recent credit-card statement. Find the balance, payment due date, minimum payment, fees, and interest charged.
Then locate each annual percentage rate, or APR. A card may apply different rates to purchases, cash advances, or other transactions. The number advertised when you opened the account may not describe every balance you have today.
For credit cards, APR expresses the interest rate on an annual basis. It does not mean that interest waits until the end of the year.
Many issuers calculate interest daily using daily balances. A lower balance for more of the billing cycle can affect the interest charged.
Practice with a deliberately simple example
Suppose a fictional balance is $1,000 and the fictional APR is 24 percent. A rough monthly illustration is $1,000 multiplied by 0.24, divided by 12, or $20.
This is teaching arithmetic, not a current offer or an exact statement calculation. Real results depend on the daily method, number of days, transactions, payments, and agreement.
If a hypothetical $50 payment covered $20 of interest and there were no fees or new purchases, $30 would remain to reduce the borrowed balance. Now compare a $70 payment under those same simplified assumptions: $50 would reduce the balance.
The exercise explains why the payment and the progress are not necessarily the same amount.
Know what the minimum does
The required minimum is the amount the statement tells you to pay by its deadline. Paying it does not mean you have paid the statement balance in full.
A small payment may leave debt outstanding for a long time. Review the statement's repayment information and avoid assuming that a comfortable monthly payment automatically means a low total cost.
A purchase grace period can allow you to avoid interest on purchases when the card's conditions are met, including paying in full on time. Not every card offers one.
Carrying a balance can affect it, and cash advances generally start accruing interest immediately. Ask the issuer how your account's grace period works before relying on it.
Compare two ways to direct extra payments
After covering required payments, some people focus extra money on the highest-rate debt; others focus on the smallest balance to pay off one debt sooner. The CFPB presents both approaches.
The rate approach generally reduces interest cost, while the smaller-balance approach may provide a motivating early milestone. Actual terms and fees still matter.
Make a small comparison sheet before choosing: balance, rate, required payment, and any special condition you need to understand. For example, a promotional end date belongs on the sheet.
Do not treat an unfamiliar collection notice, a secured loan, and a current credit-card bill as interchangeable; understand the obligation and consequences first.
Act before the next due date if possible
If the minimum is unaffordable, contact the card company promptly. Explain the difficulty, the amount you can realistically pay, and how long you expect the problem to last.
Ask what options exist and request the terms of any arrangement. A conversation does not itself change the payment agreement; confirm what has been approved.
Prepare a short script: 'My income changed. After essential costs, I can afford this amount for this period.
What options can you explain?' Keep the date, representative's name or identifier, and the response in a private note.
The immediate goal is a clear, documented next step that fits the facts, not a promise you cannot keep.
Translate one statement
Using a statement privately, write down the balance, minimum, due date, purchase APR, and last interest charge. Mark any term you cannot explain.
Use the fictional $1,000 example to calculate the rough monthly illustration, then write why it cannot predict an actual bill. Identify one question for the issuer if needed.
About this learning guide
General financial education. Examples are fictional and do not describe local residents or predict financial results.
Cultural & community review
Assessment passed This recorded version passed its cultural and community assessment.
- Reviews the cultural and community context of this editorial item.
- Source, rights and publisher checks remain separate.
- It does not score people or certify every fact.
Read the assessment record & limits
- This record applies to the identified content revision. Later changes require another assessment.
- Asset
- gj:article:gj-money-debt-apr-payments
- Engine
- ct.algorithm.cie.v1 · 1.0.1
- Receipt
- 34b792a2-18da-43de-b87f-5b2f9abbca25
- Assessed
- Revision
- sha256-0a6fb08b3fbff22ce52ce390ec31ef45f30d4d51119335204b0e111d760ef569
- Record state
- eligible · PASS
- Binding
- BOUND
Sources & verification
Source date/version: 2023-08-28 (reviewed); 2023-08-30 (modified); reviewed September 19, 2026. Scope: Credit-card APR definition
Read the sourceSource date/version: 2024-01-22 (reviewed and modified); reviewed September 19, 2026. Scope: Daily interest and different transaction APRs
Read the sourceSource date/version: 2024-09-23 (reviewed); 2024-09-25 (modified); reviewed September 19, 2026. Scope: Purchase grace periods and cash advances
Read the sourceSource date/version: 2018-11 (file version; no publication date printed); reviewed September 19, 2026. Scope: Minimum-payment limitations and repayment strategies
Read the sourceSource date/version: 2026-09-02 (reviewed and modified); reviewed September 19, 2026. Scope: Contacting issuer and assessing affordable payments
Read the sourceThis article was written with AI assistance from the linked sources. No firsthand interview or visit is implied. Source dates and limits are identified in the reporting. Advertising does not determine editorial coverage. Request a correction or read our standards.
EVERY NEIGHBOR HAS A VOICE
Keep the conversation going.
Share experiences, ask questions and link evidence for factual claims. Automated publication checks apply to each submitted version. Comments are independent community discussion, not submissions to a government body.
Sign in to join · freeCommunity standards